Roll all your debts into your home loan so you can have more cash for Christmas this year
We help home owners with multiple debts consolidate all their commitments into one payment and free up more cash each month.
Even if you have low credit score or are in arrears, we can still help you.
CLICK BELOW TO WATCH FIRST!

Next Step: Fill out the form below to start your debt consolidation journey
TESTIMONIALS
What others are saying
For Home Owners they have multiple debts, missed payments and are wanting to manage all their debts easier with one payment
MIssing payments
have mutiple debts
Feel like you are falling behind
Stressed about not getting ahead
Feeling like you are
Don't want to end up like your parents, work all your life and have little to show.
STILL NOT SURE?
Frequently Asked Questions
Here's what we usually get asked
What do I need to have ready?
Just a rough idea of your income, your current loans, your savings and what your property is worth. No paperwork needed for the call.
Who is this for?
Business owners and property investors who want to know whether they can buy their next property, and what it could do for them.
Can I use the equity in my home to buy an investment?
Often, yes. If your property has gone up in value, you may be able to borrow against that equity for a deposit. How much depends on your property's value, your current loan and lender criteria.
What if you tell me I can't do it?
Then you'll know where you stand, instead of wondering. And if it's not possible yet, I'll tell you what would need to change, so you've got something to work towards.
I've been knocked back before. Can you still help?
Often, yes. Every lender assesses income differently, so one bank's no is just one bank's no. Plenty of people who've been knocked back find there's another way to look at their situation.
Isn't now a bad time to buy?
That's what the headlines say. This call isn't about predicting the market. It's about whether the numbers work for you, and what holding a property would really cost you.
I'm self-employed. Can I still buy?
Often, yes. Some lenders can look at your business revenue, BAS, bank statements or a letter from your accountant, not just your tax return. Lender criteria apply.
Will the call affect my credit score?
No. The strategy call doesn't involve a credit check. If you decide to apply for a loan later, I'll explain what's involved before anything is lodged.
Is this financial advice?
No. I'm a credit representative, so I can help with lending and show you the numbers, but this isn't personal financial or tax advice. For tax questions, speak to your accountant.
Is a pre-approval a guarantee?
No. A pre-approval shows what a lender is likely to lend, but final approval still depends on the property, a valuation and the lender's final checks. However, 99% of our pre approvals get formal approval.
Is the wealth estimate a guarantee?
No, its an estimate based on growth and inflation assumptions, not a promise
What happens after I fill in the form?
I'll be in touch shortly to set up your call. If you'd rather lock in a time straight away, you'll be able to pick one on the next page.
How We Get You To Build Wealth
Step 1
First, we look at your full financial position and how comfortable you are taking on more debt. Together, that tells us whether you can buy an investment property and keep holding it.
It’s the most important step. Until we know what you can afford, we can’t give you the right advice. And if you’re not in a position to do this yet, I’ll tell you straight at this stage.
Step 2
Once we know you’re in a position to buy, I’ll find the right lender for your situation and get your pre-approval in place.
That gives you a clear, confirmed budget, so you can look at properties knowing exactly what you can spend and can move quickly when the right one comes up.
Step 3
With your pre-approval in place, it’s time to find the right property. Whether you search yourself or want help along the way, I’ll guide you from offer through to settlement.
I’ve bought and sold property myself, so you’ll have someone in your corner who knows what to look for and what to avoid.
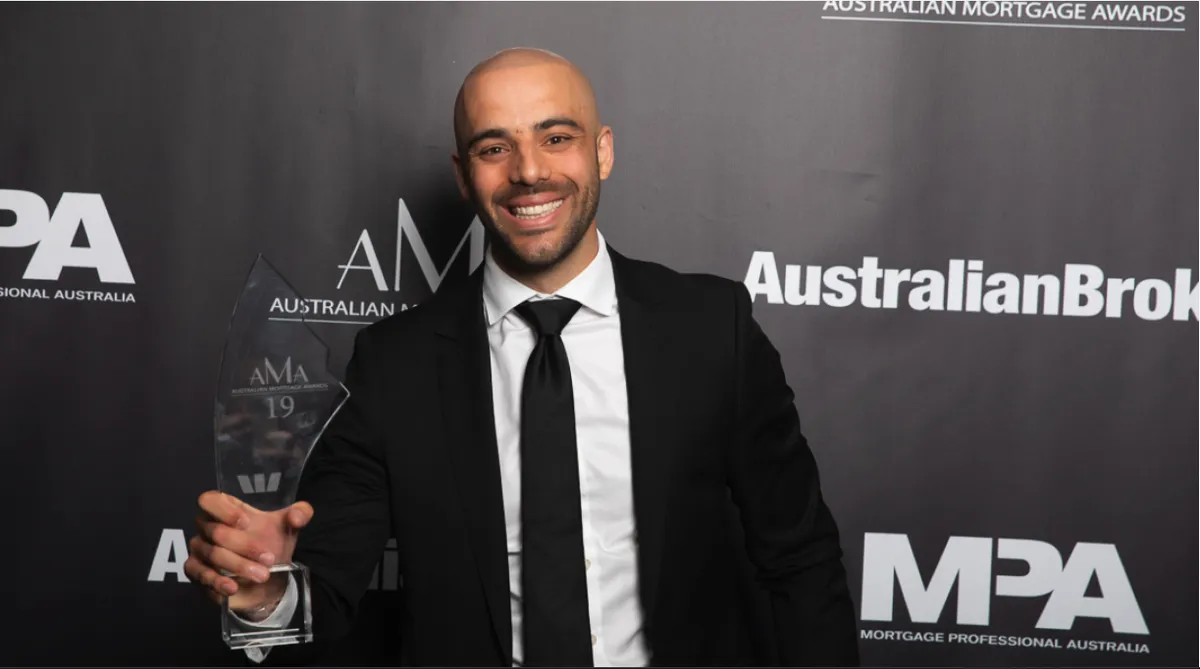
MEET THE FOUNDER
Hey,
I'm Damian Medici
I’m a specialist mortgage broker for property investors and business owners. I’m here to show you the real numbers and how you can build wealth through property. I’m not here to sell you a property, or charge you a $20k buyer’s agent fee.
I’m a bit of a numbers nerd, and my clients are better off for it. Before you buy, you’ll know exactly what the property will cost you to hold, and you’ll have a plan to keep holding it even if rates rise or the market softens.
800 + Million loans settled
Personally transacted over 10 million of property
Helped over 1,000 Families enter the property market